De Méré's Dice Paradox
When $1+1$ Is Not $2$
In 1654, a French nobleman named Antoine Gombaud, better known as the Chevalier de Méré, had a problem. Two gambling wagers that seemed identical by his reasoning behaved differently at the tables. One made money over time. The other slowly drained it.
De Méré brought the puzzle to Blaise Pascal, then thirty-one and already famous for his work on vacuum and pressure.
Pascal took the problem seriously. He wrote to Pierre de Fermat, a magistrate in Toulouse who pursued mathematics in his spare time. Over several months, the two exchanged letters dissecting de Méré’s wagers. Their exchange is now seen as the starting point of modern probability theory.
The Two Wagers
De Méré described two bets:
- Roll a single die 4 times. Bet that at least one six appears.
- Roll two dice 24 times. Bet that at least one double-six appears.
At first sight, they look equivalent.
A single die has probability $1/6$ of showing a six. The expected number of sixes in 4 rolls:
\[4 \times \frac{1}{6} = \frac{2}{3}\]A pair of dice has probability $1/36$ of showing double-six. The expected number of double-sixes in 24 rolls:
\[24 \times \frac{1}{36} = \frac{2}{3}\]Same expectation. De Méré reasoned that if the expected count of successes is the same, the probability of winning should be the same.
The First Wager: One Die, Four Rolls
The probability of no six in a single roll is $5/6$. Four independent rolls:
\[\left(\frac{5}{6}\right)^4 \approx 0.482\]So the probability of at least one six:
\[1 - \left(\frac{5}{6}\right)^4 \approx 0.518\]This wager is slightly favorable.
The Second Wager: Two Dice, Twenty-Four Rolls
The probability of no double-six in a single roll is $35/36$. Twenty-four rolls:
\[\left(\frac{35}{36}\right)^{24} \approx 0.509\]So the probability of at least one double-six:
\[1 - \left(\frac{35}{36}\right)^{24} \approx 0.491\]This wager is slightly unfavorable.
Why the Results Differ
Both wagers give the same expected number of successes: $2/3$. But the probability of winning differs. The reason: two different measures are involved.
Expectation is linear. If each trial has probability $p$ of success, then $n$ trials have expected successes $np$. Double the trials, double the expectation.
Probability of at least one success is nonlinear. It equals $1 - (1-p)^n$. Failures compound. When $p$ is small, $(1-p)^n$ stays close to 1 even for moderately large $n$.
In the first wager, the event is common enough (probability $1/6$) that one of four trials usually succeeds. In the second wager, the event is rare (probability $1/36$). Twenty-four trials aren’t enough to overcome the compounding failures.
De Méré assumed scaling trials would compensate for scaling probabilities. Expectation scales linearly, but the probability of winning does not.
Ten Thousand Rounds
The difference between 51.8% and 49.1% is small. Over a few games, luck dominates. But over hundreds of rounds, the edge becomes visible.
The figure follows both wagers through 10,000 simulated rounds, plotting each wager’s running win rate (solid: one die, 4 rolls; dashed: two dice, 24 rolls) against the exact probabilities shown as thin horizontal lines.
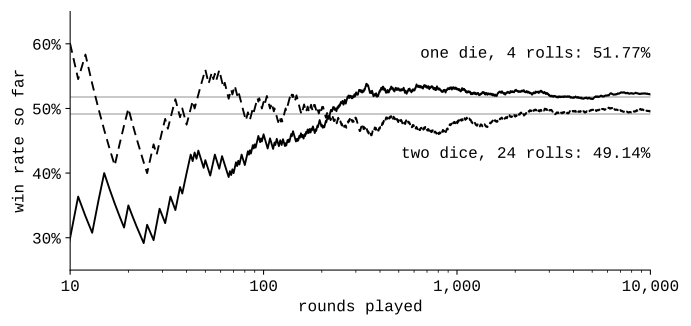
After 100 rounds the losing wager is still ahead, 51% against 46%. Only after several hundred rounds do the two curves separate in the right order, and after 10,000 rounds they sit at 52.2% and 49.6%, close to their exact values.
The Same Trap Today
The confusion between expectation and probability appears far beyond dice.
Lotteries. A ticket costing $2 with a 1-in-10-million chance at $10 million has expected value near $1. Buy a million tickets and your expected return is about $1 million. But your probability of winning even once is still only about 10%.
Medical screening. A test with 99% sensitivity and 1% false positive rate sounds reliable. If the disease prevalence is 0.1%, most positive results are false positives. The expected number of true positives per thousand tests is about 1. The probability that your positive result is correct is only about 9%.
Rare risks. The expected number of fatal accidents on a commute might be 0.0001 per trip. Over 10,000 trips, the expectation is 1. But the probability of at least one fatal accident is about 63% (by $1 - e^{-1}$), not 100%. Expectation and probability diverge most sharply for rare events repeated many times.
The Pascal-Fermat Correspondence
Pascal’s letters to Fermat did more than resolve a gambling puzzle. They introduced methods for counting arrangements, dividing stakes fairly, and reasoning systematically about future outcomes. Within a generation, Christiaan Huygens had turned that correspondence into the first textbook on probability, and Jacob Bernoulli would use Pascal’s methods to prove the law of large numbers. By the eighteenth century, Laplace had extended these ideas to astronomy, insurance, and the theory of errors.